
Tipperary head of SVP wants tobacco style warning on moneylenders advertising high cost loans

BORROWERS SHOULD BE TOLD THE TRUE COST OF LOANS
The Society of St Vincent de Paul (SVP) is seeking to have all licensed moneylenders carry a tobacco style high cost loans warning on their advertising and literature.
In a submission to the Department of Finance SVP has said that it is astonishing that no such warning is currently required in advertisements related to licensed moneylending.
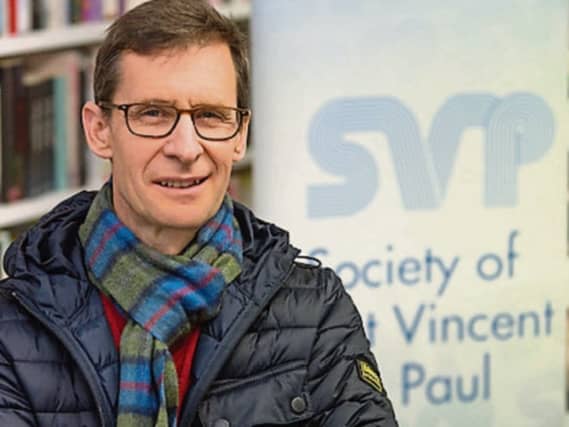
Clonmel man Kieran Stafford, national president of the SVP, said repaying a high cost loan is a very heavy burden for households that are struggling and can lock them into a cycle of debt and poverty.
According to the Central Bank, while moneylenders are required to provide information about the high cost nature of the loan to their customers, this is typically provided in the moneylending agreement which must be signed by the customer, and is not a requirement for the advertisement of licensed moneylending loans.
The Society says that “Warning: This is a high cost loan” should be on all moneylending advertisements and literature and the warning should also point out that alternatives to high cost loan offerings may be available and that people should check their options before borrowing. There are an estimated 330,000 customers of moneylenders in Ireland.
SVP also believes that there should be a statutory maximum cost of credit which can be charged by a moneylender and that consumers should have better access to sources of low-cost credit. This could be achieved through the introduction of a statutory interest rate cap.
“This should be done at the same time and in conjunction with the introduction and strengthening of other measures to protect vulnerable customers of moneylenders,” says Caroline Fahey, SVP Head of Social Justice.
“These other measures should include better access to sources of low cost credit for low income households, enforcement of the Consumer Protection Code for Moneylenders and better protection of customers of moneylenders, including better information, financial education and more inclusive mainstream banking services”
“The main considerations for SVP and the people we assist are the total cost of credit, including charges; how manageable the repayments are; the alternatives available;
the provision of clear information which will allow customers to make informed decisions about taking out moneylender loans and the introduction, strengthening and monitoring of measures to protect customers of moneylenders.” she said.
Kieran Stafford, SVP National President added - “SVP members regularly report inappropriate lending to very vulnerable households who do not have the capacity to repay the loan.
It is our experience that people tend to use moneylenders when they have limited access to other sources of credit and they may be worried about cutting themselves off from this source of credit by reporting abuses within the sector.
“Living on a low income and having a poor credit rating limits the options for people who are trying to access credit. Moneylenders are meeting a need for access to credit but often
at a cost which people who are better off and who have other options would baulk at. Repaying a high cost loan is a very heavy burden for households that are struggling and can lock them into a cycle of debt and poverty.”
“Access to affordable credit is essential for individuals on a low income, whether in or out of work. Moneylenders tend to engage in heavy advertising at times when low income households are under financial pressure, for example back to school and Christmas, and it is important that customers know at first glance that the adverts they are seeing are for high cost credit.”